
Should I combine my pensions?
Combining your pensions can make retirement planning a lot simpler, but is it right for you? We explore the pros and cons of pension consolidation.
If you’ve worked for different employers during your career, you’ve probably accumulated several pension pots along the way. Keeping track of them can be a bit of a headache. It can also make planning your retirement more complicated.
Combining your pensions, also known as ‘pension consolidation’, can cut down on admin and may even help you save on costs, meaning you have more money to enjoy in retirement.
Here, we explore what pension consolidation involves and some of the pros and cons to consider.
What is pension consolidation?
Pension consolidation means bringing all your pensions together in a single pension pot. You do this by transferring your pension savings to your chosen pension provider.
Benefits of combining your pensions
There are several advantages to consolidating your pensions.
They're easier to manage
Combining your pensions can cut down on admin. You won’t have to log in to multiple accounts or sift through stacks of statements.
It’s also easier to see where your pension money is invested. That way, you can make sure you have the right mix of investments for your goals and attitude to risk. If you’re not confident choosing investments, you can consolidate with a provider who can choose investments for you.
You’ll have a clearer view of your savings
It’s much simpler to track the progress of your savings when everything is in one place. It’s easier to see if you’re on track to meet your retirement goals and work out how much more you need to save.
You could lower your costs
If you consolidate your pensions with a lower-cost provider, you could even save on fees. Most pension providers charge an annual percentage fee for managing the pension, plus a separate charge for managing the investments themselves. These costs can add up over time, especially if you’re saving for a long-term goal like retirement.
The chart below shows that reducing your fees by 0.3% a year over 25 years could save you more than £13,000 on a £50,000 pension pot or nearly £40,000 on a £150,000 pot. This assumes a 5.5% annual return and that you don’t make any further pension contributions.
How a 0.3% saving in fees adds up over 25 years
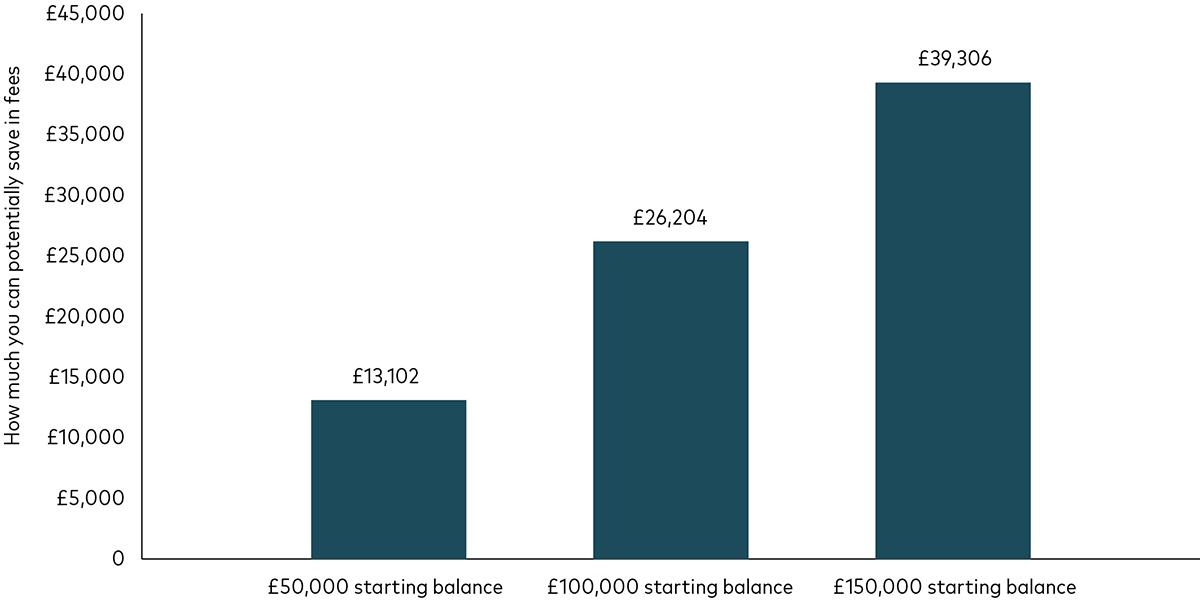
Notes: This hypothetical scenario is for illustrative purposes only and doesn’t represent a particular investment or its expected returns. It assumes annual returns of 5.5% before fees.
Source: Vanguard calculations.
Disadvantages of combining your pensions
Before you transfer your pensions, there are some potential drawbacks to consider.
You might have to pay exit fees
Some pension schemes might charge exit fees for transferring your funds. These fees could eat into your retirement savings.
You could give up valuable guarantees
Some pensions offer valuable guarantees, such as a guaranteed income or protected tax-free cash (this allows you to take more than the usual 25% of your pension tax-free). If you transfer to another provider, these benefits will most likely be lost. If you have a defined benefit1 – or ‘final salary’ – pension, which pays a guaranteed income, consolidation is unlikely to be suitable. Make sure you check your pensions’ terms and conditions. If you’re unsure what type of pensions you have, or find the details confusing, speak to a financial adviser2.
You could lose employer contributions
If you have a workplace pension which you’re currently paying into, transferring your pension may mean missing out on employer contributions. This could really reduce how much income you have in retirement.
Speak to a financial adviser if you’re not sure about anything.
How to consolidate your pensions
If pension consolidation is right for you, there are three main steps.
Find your pensions
List all your pensions and their details. If you’ve lost track of any, use the government’s free pension tracing service.
Choose a pension
Compare providers based on their fees, investment options and customer service. Check that your chosen pension accepts transfers.
Start the transfer
Apply for the transfer through your chosen provider, who will usually manage it for you.
You’ll need to have stopped contributing to a workplace pension to transfer it in full. If you’ve already taken benefits from a pension, such as tax-free cash or a taxable income, you must do a full transfer.
Consolidating your pensions with Vanguard
At Vanguard, we’ll work with your current pension providers on the transfer process and combine your pensions into one pot.
We offer a range of options to help you invest your pension savings. You can build your own pension portfolio from our wide range of low-cost funds.
Or you can keep things simple with one of our Target Retirement Funds, which are ready-made retirement portfolios. Simply choose one based on when you plan to retire and we do the rest. (If you decide to retire sooner or later, you can always switch to a fund with a different target retirement date.) As you get closer to retirement, we'll start moving you out of higher-risk, higher-reward investments into more stable ones. This is because your investments would have less time to recover if the market fell.
If you want more of a helping hand, our managed service will choose your investments based on your attitude to risk. And we’ll make sure your investments stay at the right risk level for you, every step of the way.
Find out how to transfer your pension to Vanguard and what to know before starting a transfer.
1 Defined benefit (DB) pensions pay a guaranteed income depending on your final or average salary and are funded by employers. In general, DB pensions are usually not suitable for consolidation.
2 If you have a DB pension valued at more than £30,000 or a defined contribution (DC) pension with guaranteed benefits, you must, by law, get advice from a regulated financial adviser before transferring. (A DC pension is a pension scheme that builds up a ‘pot’ of money to pay you a retirement income. It can be a workplace pension scheme set up by your employer or a personal pension scheme set up by you.)

Investment risk information
The value of investments, and the income from them, may fall or rise and investors may get back less than they invested.
Any projections should be regarded as hypothetical in nature and do not reflect or guarantee future results.
Eligibility to invest in a Vanguard Personal Pension depends on your individual circumstances. Please be aware that pension and tax rules may change in the future and the value of investments can go down as well as up, so you might get back less than you invested. You cannot usually access your pension savings or make any withdrawals until the age of 55, rising to the age of 57 in 2028.
If you are not sure of the suitability or appropriateness of any investment, product or service you should consult an authorised financial adviser. Please note this may incur a charge.
Your transfer will be sent to us as cash or shares (Vanguard funds only). During the transfer period any cash will not be invested so you could miss out on any increase in the value of your investments should the market rise.
The Vanguard Target Retirement Funds may invest in Exchange Traded Fund (ETF) shares. ETF shares can be bought or sold only through a broker. Investing in ETFs entails stockbroker commission and a bid-offer spread which should be considered fully before investing.
For further information on risks please see the “Risk Factors” section of the prospectus on our website.
Important information
This is a marketing communication.
Vanguard only gives information on products and services and does not give investment advice based on individual circumstances. If you have any questions related to your investment decision or the suitability or appropriateness for you of the products described, please contact your financial adviser.
For further information on the fund's investment policies and risks, please refer to the prospectus of the UCITS/NURS and to the KIID/KII before making any final investment decisions. The KIID/KII for this fund is available, alongside the prospectus via Vanguard’s website.
This is designed for use by, and is directed only at, persons resident in the UK.
The information contained herein is not to be regarded as an offer to buy or sell or the solicitation of any offer to buy or sell securities in any jurisdiction where such an offer or solicitation is against the law, or to anyone to whom it is unlawful to make such an offer or solicitation, or if the person making the offer or solicitation is not qualified to do so. The information is general in nature and does not constitute legal, tax, or investment advice.
Potential investors are urged to consult their professional advisers on the implications of making an investment in, holding or disposing of [units/shares], and the receipt of distribution from any investment.
Vanguard will manage your investments in the Managed SIPP on your behalf. You will not be able to place trades on your own account.
The Authorised Corporate Director for Vanguard LifeStrategy Funds ICVC is Vanguard Investments UK, Limited. Vanguard Asset Management, Limited is a distributor of Vanguard LifeStrategy Funds ICVC.
For investors in UK domiciled funds, see our summary of investor rights and is available in English.
Issued by Vanguard Asset Management Limited, which is authorised and regulated in the UK by the Financial Conduct Authority.
© 2026 Vanguard Asset Management Limited. All rights reserved.
5921538